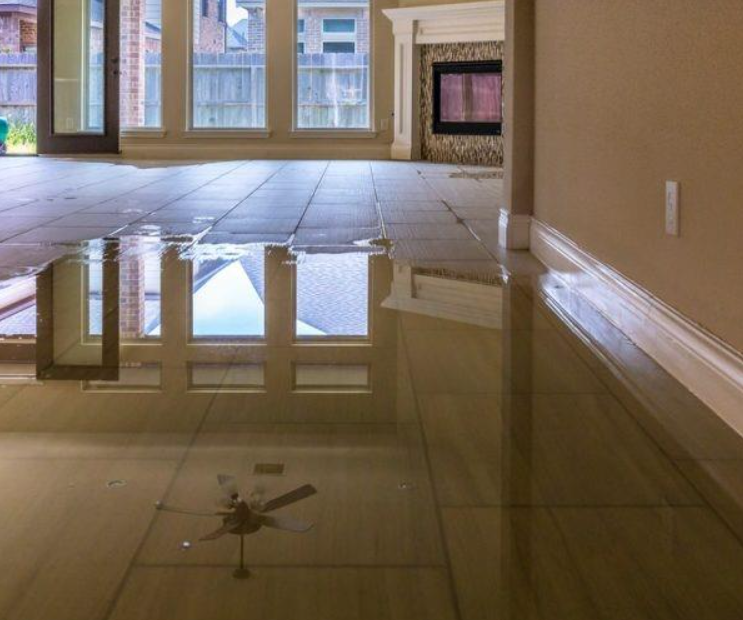
A pipe bursts in your Crown Point basement. A summer storm tears shingles off your Valparaiso roof. You call your insurance company and within a day the adjuster hands you a name: “Here’s the contractor we work with. They can start Monday.”
It sounds convenient but many homeowners walk away from that call believing they have to use that company an in most cases, you don’t.
At AmeriClean, we’ve helped Northwest Indiana families recover from water, fire and mold damage for 40 years and this is one of the questions we hear most. Here’s what you need to know.
The short answer: it’s your home and usually your choice
In Indiana, insurers commonly keep a list of “preferred” or “network” contractors. Those lists are recommendations, not requirements. Indiana Farm Bureau Insurance, one of the state’s largest insurers, tells its own policyholders they are free to choose any contractor they like for a covered claim. The National Association of Insurance Commissioners takes the same position: homeowners may hire any properly licensed contractor that meets state and local rules.
That means you can:
- Use the contractor your insurer suggests
- Hire a local company you already know and trust
- Get several estimates and compare before deciding
Your insurer cannot deny a covered claim simply because you chose a different qualified contractor.
The exceptions you should know about
“Usually” matters. There are three situations where your choice can be limited or come with strings attached.
- An “option to repair” clause. Some homeowners policies allow the insurer to choose to repair or replace damaged property itself instead of paying you cash. If your policy contains this clause and the insurer invokes it, they may control who does the work. These clauses are not in every policy, so read yours or ask your agent directly.
- A “managed repair” program you agreed to. Some policies offer a discount in exchange for agreeing to use the insurer’s network. If you signed up for that, the terms you accepted apply.
- Even when you choose your own contractor, the insurer decides what it considers a reasonable cost to repair. If your contractor’s bid is higher, you may need to resolve the difference. Stay tuned to our next blog post explaining how that works.
Why Indiana has rules for auto repair but not home repair
You may have heard that Indiana law guarantees your right to pick your own auto body shop. That’s true: the state has a separate chapter of the insurance code governing auto repair claims. There isn’t a matching statute written specifically for home repairs. Your right to choose a home restoration contractor comes from your policy and standard claims practice. That’s exactly why reading your policy matters.
Preferred contractor vs. your own contractor
| Insurer’s preferred contractor | Contractor you choose | |
| Who they’re accountable to | Often has an ongoing agreement with the insurer | Works for you, under your contract |
| Pricing | Usually agreed in advance with the insurer | Reviewed by the adjuster; differences negotiated |
| Warranty | Insurer may stand behind the work | Contractor’s own written warranty |
| Local knowledge | Varies; may be regional or national | You can choose someone local to Lake and
Porter counties |
Neither option is automatically better. What matters is that the decision is yours, made with full information.
Five steps to protect your claim when you choose your own contractor
- Ask your adjuster in writing whether your policy contains an option-to-repair or managedrepair provision.
- Tell the insurer in writing which contractor you’ve selected.
- Stop further damage right away. Your policy almost certainly requires you to take reasonable steps to prevent more damage. Emergency water extraction or board-up is not something to delay while you decide on a rebuild contractor.
- Get a written, itemized estimate and share it with the adjuster early, before work begins.
- Get a written contract that meets Indiana’s Home Improvement Contracts Act.
How AmeriClean helps Northwest Indiana homeowners
When you choose AmeriClean, you get a local, licensed and insured restoration team based in Merrillville and available 24/7, 365 days a year. Here’s what we do on insurance-related jobs:
- Water damage mitigation to stop water from spreading into walls, floors and framing
- Fire damage restoration to bring your home back after fire and smoke
- Mold remediation to remove mold safely and address the moisture behind it
- Photo documentation and itemized estimates your adjuster can review
Learn More: How Restoration Companies Work With Insurance Claims
One thing we won’t do is take over your claim. Indiana law doesn’t allow contractors to act as public adjusters and we think that’s a good rule. You stay in control of your claim; we make sure the restoration side is documented and done right.
Dealing with water, fire or mold damage in Merrillville, Crown Point, Valparaiso or anywhere in Northwest Indiana? Call AmeriClean at 219-641-3711, day or night, or book online for a free estimate.
This article is general information, not legal advice. Policies differ; review your own policy and talk with your insurance agent or an attorney about your specific situation